Debt and cash safety
Extra debt payments can reduce interest while also reducing flexibility. Clearflow keeps the cash-safety tradeoff visible.
 Clearflow
Home
Why Clearflow
A budget can tell you what you meant to spend. A tracker can tell you what already happened. Clearflow is for the step in between: checking what a payment, purchase, or extra debt payment will change.
See how it works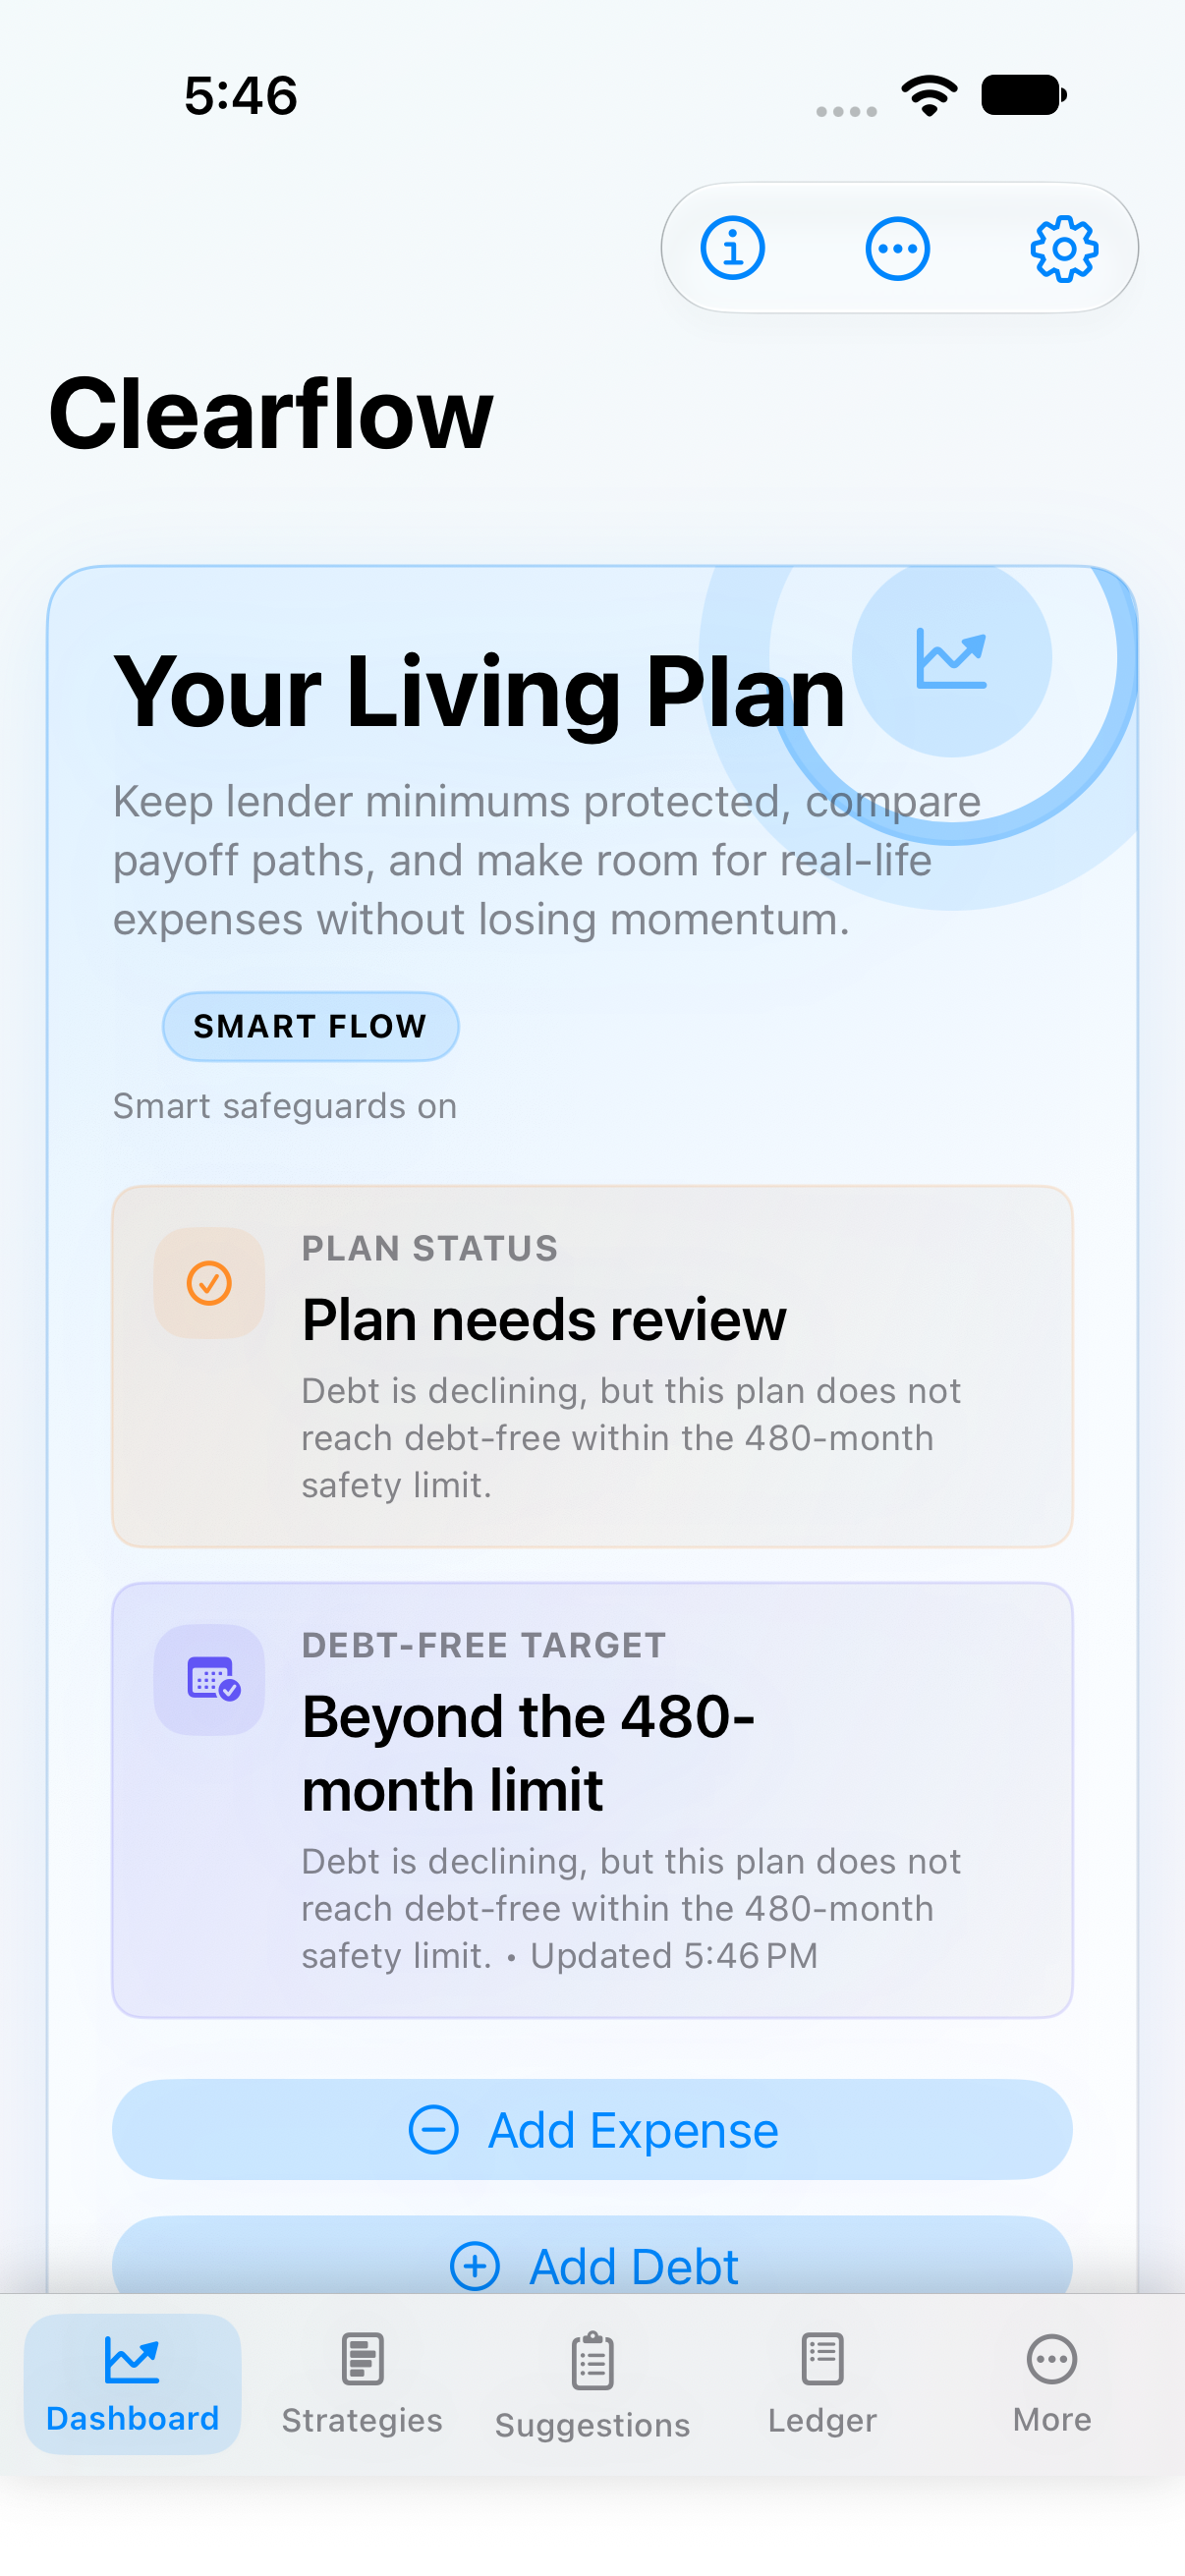
The short version
It is for the ordinary situations that make a plan hard to read: an early paycheque, a large bill, an extra debt payment, or a goal that has moved.
A useful comparison
Clearflow is not meant to replace every money tool. It covers the part that is usually left to a spreadsheet, a calculator, or guesswork.
| Tool type | Best at | What may still be missing | Clearflow's role |
|---|---|---|---|
| Monthly budget app | Assigning money to categories for a month. | A month-by-month view can hide what a decision does to the next few months. | Keeps upcoming income, bills, and choices on the same timeline. |
| Expense tracker | Showing what has already happened. | Past spending does not answer whether a new payment fits. | Separates confirmed activity from the events you are still expecting. |
| Debt calculator | Estimating payoff dates or interest. | The answer may ignore bills, cash reserves, or a planned purchase. | Compares payoff options with the rest of the month still in view. |
| Spreadsheet | Flexible custom analysis. | Someone has to keep the dates, formulas, and assumptions consistent. | Gives you a focused model with clear statuses and fewer moving parts. |
| Clearflow | Checking what a decision changes. | It is only as good as the information you enter and maintain. | One dated plan for income, bills, debt, savings, and purchases. |
What stays connected
Extra debt payments can reduce interest while also reducing flexibility. Clearflow keeps the cash-safety tradeoff visible.
A savings target has a date, a contribution pattern, and a relationship to the rest of the plan. See those pieces together.
Model a planned purchase before it arrives so you can see which goals or future payments it displaces.
Keep a projection useful without confusing it with a reconciled account balance or a transaction that actually happened.
The point
Before you move the money, see what it changes.
Clearflow does not tell you what to choose. It puts the timing, cost, and tradeoff where you can see them.
Before you rely on a number
Clearflow is planning software, not financial, legal, tax, investment, or accounting advice.
A forecast is only as reliable as the amounts, dates, frequencies, balances, and assumptions behind it. Review the source details when a choice matters.
Core planning is designed to work without a bank connection. That keeps the user-entered plan explicit, but it also means you are responsible for keeping it current.
Next step
It covers setup, the main screens, and a simple review routine.